
PLANNING, INVESTMENTS, AND YOUR TAXES
Financial planning built for families
As a husband and father, I understand the unique demands that come with building a career, raising a family, and planning for the future at the same time. That perspective shapes the way I work.
I offer one relationship for dual-income parents, bringing taxes, investments, estate, insurance, and college planning together so you have fewer moving parts to manage.
Retirement
Taxes
Investments
Estate Coordination
Insurance
College Tuition
Retirement Taxes Investments Estate Coordination Insurance College Tuition
Here's the setup you're probably working with.
A CPA you see once a year. Someone managing the investments. Maybe a planner. An attorney's number in a drawer somewhere.
Nobody talks to anybody. You sit in the middle, forwarding documents between people you pay.
Both of you work. The kids have calendars of their own. The one thing you don't have is time to be the coordinator. That's the job I took.
WHO WE SERVE
Built for Families Like Yours
I work with dual-income parents in Director-level roles and above. Careers in full swing, kids at home, and a financial life that has outgrown the time you have to manage it.
If that sounds familiar, start here.
THE PLAYBOOK
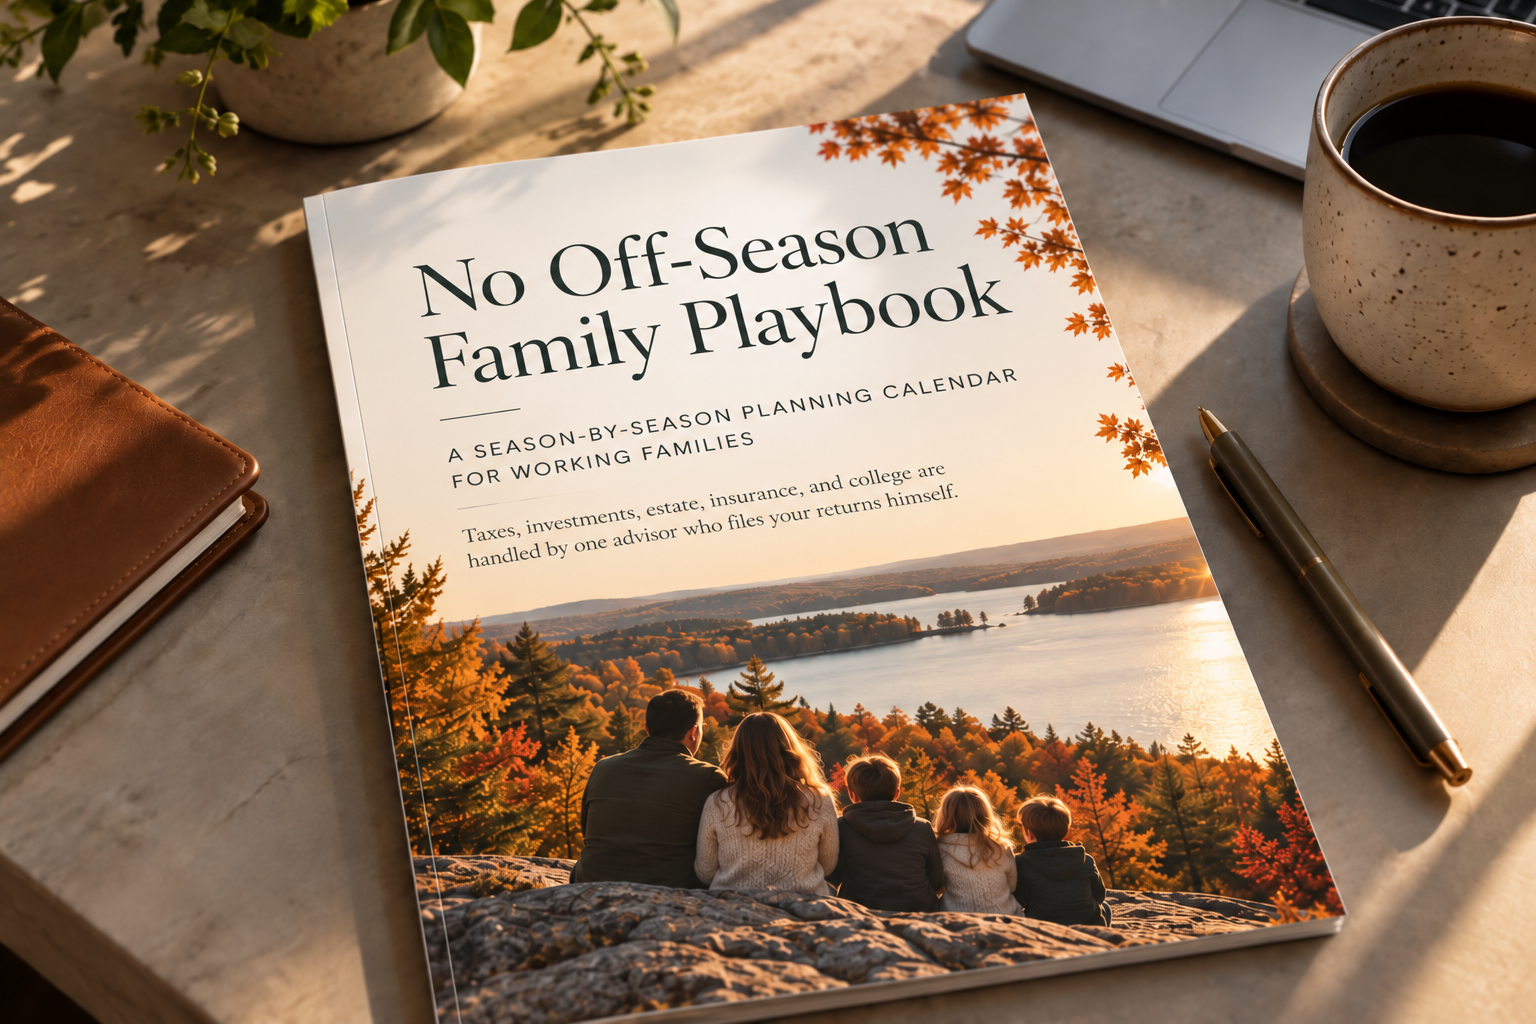
A Plan for Every Season
The No Off-Season Family Playbook is our year-round planning calendar. Every season has defined work, and you always know what we're working on and why. Nothing waits for an annual meeting to surface.
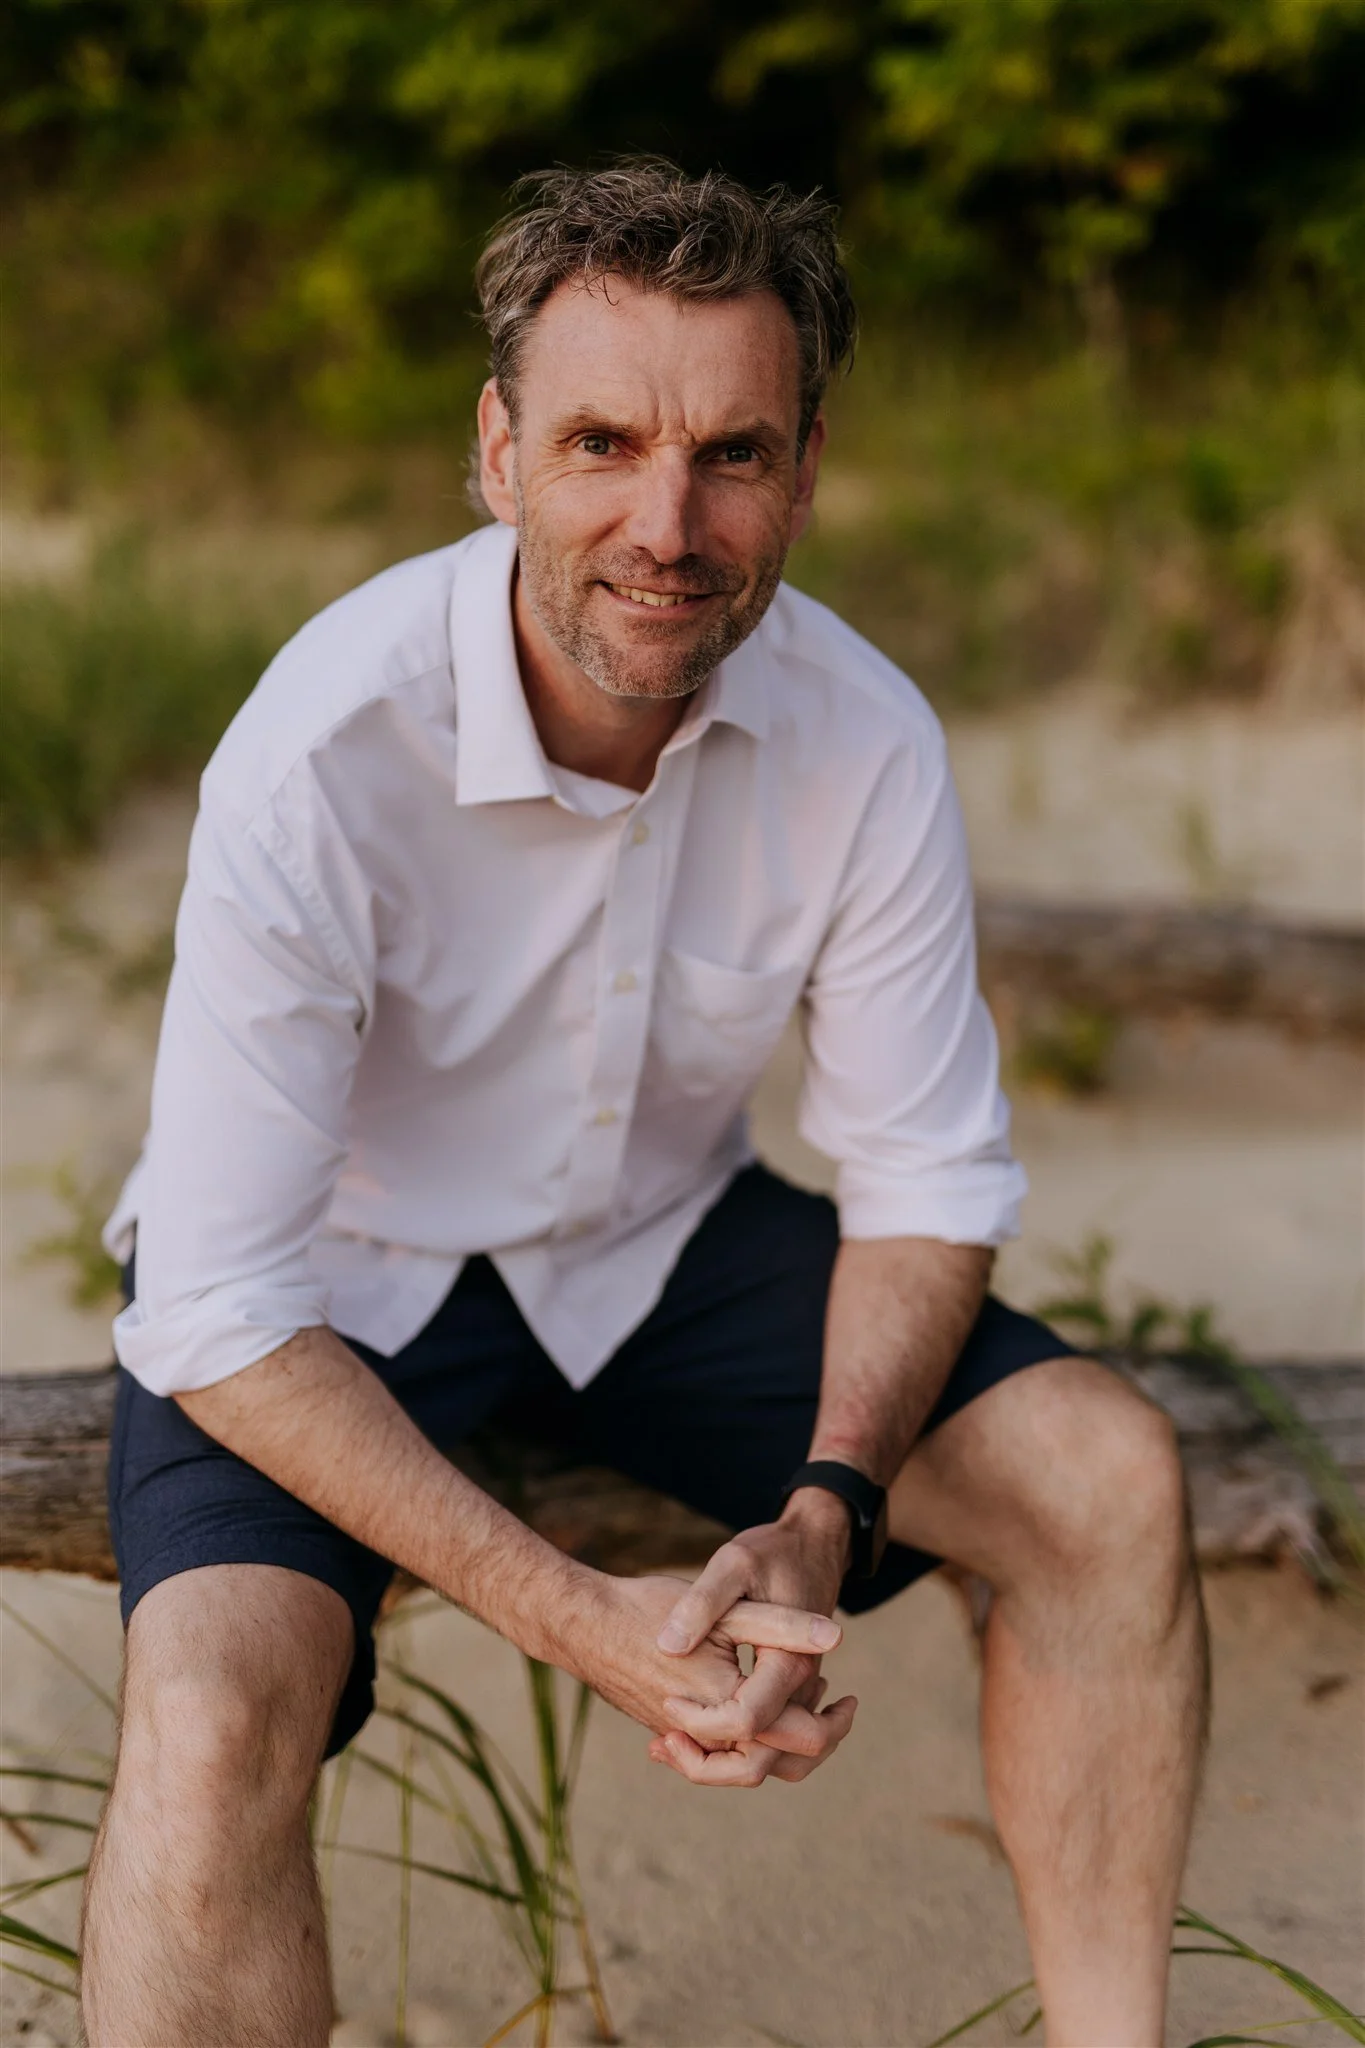
MEET PAUL
One advisor, not a hand-off
I’m a Certified Financial Planner® and Enrolled Agent, and I file tax returns myself for families. TAMMA is named after my wife, Theresa, and our four kids, including triplets.
How It Works
Schedule a conversation
Pick a time that works. No forms, no prep.
We Meet
I learn what's going on in your personal and financial life. You learn how I work.
We Decide
If we're aligned, we map out next steps. If we're not, we'll say so.
Questions Families Ask Us
-
It means one person handles your planning, taxes, investments, and the coordination between them. That level of service used to be reserved for families with tens of millions. I built it for working families with full careers and kids at home. Instead of three or four professionals who never talk to each other, you have one relationship and one plan.
-
This is the question I hear most. The honest answer is that it depends on trade-offs you should be able to see before you make them. I build college funding into the same plan as retirement, so a decision in one shows up in the other ahead of time. College plans get reviewed every fall, timed to FAFSA season.
-
Usually, because the person doing your taxes in April isn't the person who watched your financial decisions all year. I file your tax return, and tax planning happens year-round. Withholding, equity comp, and charitable timing get reviewed before December, not explained after the fact.
-
The first step is knowing what you actually own, because RSUs, options, and purchase plans are all taxed differently. Most families I meet are holding more company stock than they would ever choose to buy on purpose. The plan is designed to decide ahead of each vest what gets sold, what gets kept, and what the tax bill looks like either way.
-
That question is the reason a lot of families finally call. The answer lives in documents most households haven't touched since the first baby came home: wills, guardianship, beneficiaries, life insurance. I build estate and insurance reviews into the planning calendar so they get updated when life changes, not rediscovered in a crisis.
-
No. I don't set an asset minimum. The service is built for senior-level parents whose financial lives have outgrown the time they have to manage them. The first conversation is where we figure out together whether the value matches the cost for your situation. If it doesn't, I'll say so.
-
I'm based in Commerce Township, Michigan, and most of the families I serve are here. I also work with families across twelve states. Planning, tax filing, and reviews all work the same way whether we meet at a table or on a screen.
-
The difference is the space between them. Your advisor and your CPA each see half the picture, and neither one is responsible for how the pieces fit together. I am. Planning, tax filing, and investments live in one relationship, built so nothing falls through the cracks.
-
It's a conversation, not a pitch. I learn what's going on in your personal and financial life, you learn how I work, and we decide together whether it makes sense to keep talking. If we're not the right fit, I'll say so and point you in a better direction.
PODCAST
Welcome to the Emotional Balance Sheet, the financial planning podcast for working parents who are building careers and raising kids at the same time.
If you and your spouse are both senior-level professionals, raising kids in school or college, and are tired of stitching together four different specialists to run your financial life, this show is built for you.
Each conversation tackles the planning conversations real families are having: education costs, retirement timing, equity compensation, career transitions, estate coordination, and the emotional weight that lies beneath it all.
What Does Enough Mean to You?
Money is a number. Enough is a story. Make sure you are writing your own.